
Home Equity Line of Credit (HELOC)
A Home Equity Line of Credit (HELOC) lets you turn your home’s value into a flexible financial resource with convenient access to funds and competitive rates. Borrow only what you need, when you need it—whether you’re upgrading your home, consolidating debt, or covering major expenses.
With a HELOC, your home’s equity works for you, offering an affordable way to manage high costs and support your financial goals.
Contact Us
HELOC Benefits
FlexPath Home Equity Line Of Credit Details
Ideal if you want all the flexibility of a traditional HELOC, with a fixed-rate option.
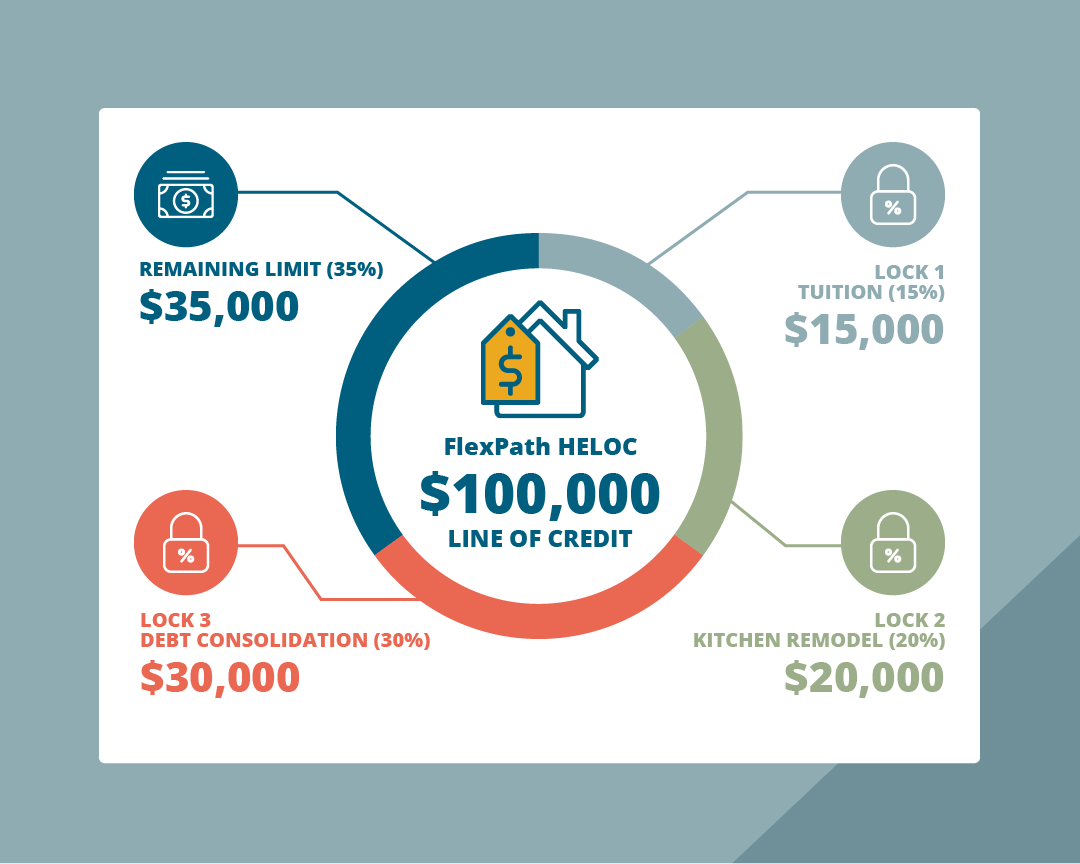
Our FlexPath HELOC1 was designed to give you more control over how you borrow and repay. You’ll enjoy the ability to lock in a rate for predictable monthly payments when you want payment certainty, and continued access to your remaining available variable rate credit during the draw period.
- Lock up to three fixed segments at one time
- Flexible lock repayment terms—7, 10, 15, or 20 years
- Rates as low as 7.00% APR*1
- No closing costs and no annual fees
- Borrow from $10,000 to $400,000
- 10-year draw period with 20-year repayment term
Instead of choosing between the flexibility of a traditional HELOC and the predictability of a fixed-rate loan, a FlexPath HELOC lets you enjoy the advantages of both.
Refinancing? Get a 1% rebate up to $4,000
Transfer your HELOC or fixed second mortgage from another lender into a FlexPath HELOC and receive a 1% rebate applied to your principal.^
- Available on balances transferred from another financial institution
- Rebate is applied directly to your loan principal at closing
- Existing CommonWealth HELOCs and second mortgages are not eligible
Wealth Home Equity Line Of Credit
A great option if you’re looking for higher borrowing limits and flexible access
Put your home’s equity to work with a Wealth HELOC2 offering higher borrowing limits and structured repayment terms. A strong option for larger expenses or long-term financial planning.
- Rates as low as 7.00% APR*2
- Access up to 80% of your home’s equity (CLTV)
- Credit lines from $10,000 to $500,000
- 10-year draw period for ongoing access
- 20-year repayment term for manageable payments
CommonWealth Central CU Membership Benefits
-
Financial Wellness Services
Get the tools, resources, and support you need to take control of your finances and plan for the future.
-
Online and Mobile Banking
Manage your money anytime, anywhere. Check balances, transfer funds, pay bills, and deposit checks from your phone or computer.
-
Mortgage Calculators
Quickly estimate monthly payments, compare loan options, and see how different rates and terms impact your budget before you apply.
-
Upcoming Seminars/Webinars
Join our upcoming seminars and webinars to learn practical financial tips and get expert guidance.
-
Loan Protection
Loan protection offers peace of mind by covering your payments if you experience a job loss, disability, or pass away.
What Our Members Are Saying
HELOC FAQ
-
How does a HELOC work?
A HELOC (Home Equity Line of Credit) is like a credit card but backed by your home’s equity. You get access to a set credit limit and can borrow what you need, when you need it. As you pay it back, your available credit replenishes—giving you ongoing flexibility.
Your HELOC has two phases:
- 10-year draw period – Borrow as needed and make interest-only payments
- 20-year repayment period – No more borrowing, just paying back the balance over time
It’s a great way to manage home projects, consolidate debt, or cover big expenses—without taking out multiple loans.
-
What can I use my HELOC for?
A HELOC offers flexible access to funds for a variety of financial needs, including:
- Upgrading your home with renovations or repairs
- Consolidating high-interest debt into a lower, more manageable payment
- Covering major life expenses like weddings, tuition, or medical bills
- Making a large purchase without depleting your savings or turning to credit cards
- Other needs
-
How can I access my HELOC funds?
You can conveniently access your HELOC funds by:
- Transferring money through online or mobile banking
- Requesting a check
- Moving funds into your checking account
-
What is the difference between a HELOC and a home equity loan?
Both options allow you to use your home’s value to access funds, but they work differently. A home equity loan provides a one-time lump sum with fixed payments. A HELOC offers a revolving credit line that you can draw from up to your limit, and as you pay it down, funds become available again.
-
Can I pay off my HELOC early?
Yes. You can make extra payments or pay your balance in full with no penalties with our HELOC options. Paying down your balance sooner can help reduce the total interest you pay over the life of the loan and free up available credit.
-
Do I have to use the full credit line amount?
No. With a HELOC, you can draw funds in the amount you choose, up to your approved credit limit. You’ll only pay interest on the amount you borrow—not the full approved limit.
-
Can I have a mortgage and a HELOC at the same time?
Yes. As long as you have enough equity in your home, you can carry both loans at the same time.
-
What happens if I have a HELOC and I sell my home?
If you sell your home, your HELOC must be paid off at the closing. The remaining balance is typically paid using the proceeds from the sale. Once the balance is paid in full, the HELOC account is closed.
Explore More Ways to Borrow
Personal Loans
Your Goals, Your Loan
A Personal Loan gives you flexible funds for what matters most—home projects, big purchases, or unexpected expenses!
Mortgages
Your Path to Homeownership
Buying a home or refinancing your mortgage? Explore your options and see what works best for you—whether it's securing a loan for your dream home or refinancing to lower your rate.
WealthMatters
Learn. Grow. Build Confidence.
Take control of your finances with quick, interactive lessons! Learn to save smarter, budget better, and plan for the future—all at your own pace. Ready to make smarter money moves?
^^Home Equity Line of Credit 1% Rebate offer valid only on HELOC or Fixed Second Mortgage balances transferred from another financial institution. A 1% rebate credit will be applied to the principal balance at loan closing, up to a maximum of $4,000. Refinancing of existing CommonWealth HELOC or Fixed Second Mortgage loans does not qualify. If the HELOC is closed within 24 months, all waived fees associated with loan origination will be reimbursed to the credit union. Rebate incentives of $600 or more are subject to IRS reporting on Form 1099-MISC. Click here to view Home Equity Line of Credit Early Disclosures.
*APR = Annual Percentage Rate. The rate you receive will be based on certain creditworthiness. All rates are subject to approximate loan term limits, and certain restrictions may apply. Rates, terms, and conditions are subject to change without notice. Minimum loan amounts are required for some loan terms. Contact us for minimum loan amounts by term, maximum loan amounts, and loan-to-value requirements. Additional conditions apply.
1FlexPath HELOC: The variable APR on balances not locked at a fixed rate is based on the Prime Rate plus a margin of 0.00% to 5.00%, based on your credit rating. The variable APR is subject to change at the end of the month based on the current highest Prime Rate published in The Wall Street Journal “Money Rates” table. The minimum APR is 4.00%, and the maximum APR is 18.00%. You may lock a portion of your outstanding balance at a fixed rate up to three segments with term options of 7, 10, 15, and 20 years. The fixed rate is based on the current one-year U.S. Treasury rate plus a margin based on the term and your credit rating. Contact us for current rates. During the draw period, you may borrow up to your available credit limit. All outstanding balances, including fixed-rate balances, count toward your credit limit and reduce the amount available to borrow. Monthly payments on variable-rate balances are based on accrued interest. Fixed-rate balances require monthly principal and interest payments during the lock term. After the draw period ends, you may no longer borrow funds and will make principal and interest payments on remaining balances. FlexPath HELOC are available from $10,000 to $400,000, up to 80% combined loan-to-value (CLTV). There are no application processing fees, closing costs, prepayment penalties, or early closure fees. If you close your line within 24 months, you must reimburse the credit union for applicable third-party origination costs paid on your behalf and not collected at account opening. A $150 finance charge applies if you unlock a balance previously locked at a fixed rate.
2 Wealth Home Equity Line of Credit up to 80% CLTV with loan amounts of $10,000 to $500,000. The variable APR is based on the Prime Rate plus a margin of 0.00% to 5.00%, based on your credit rating. The APR is subject to change at the end of the month based on the current highest Prime Rate published in The Wall Street Journal “Money Rates” table. The minimum APR is 4.00%, and the maximum APR is 18.00%. During the draw period, you may withdraw (advance) funds up to your credit line limit and pay interest accrued on that balance monthly. After the draw period, you may not withdraw any more funds from the line. Your loan is then amortized, and you begin to pay the principal and interest monthly. Borrower is responsible for closing costs ranging from $450 to $1,500, including appraisal and escrow.
Real Estate loans are available for owner-occupied properties in the state of California only. HELOCs are available for existing CommonWealth members and to new members residing in the following counties in California: Alameda, Contra Costa, Merced, Monterey, San Benito, San Mateo, Santa Clara, and Santa Cruz.
Membership in CommonWealth is required.
You Are Leaving Our Site.
You are about to leave CommonWealth Central Credit Union's website. We have provided this link to a business partner site or as a courtesy to a resource site. A business partner site will be identified with our logo; resource sites will not have our logo and will not be endorsed by CommonWealth. Please remember that our Privacy Policy is no longer in effect when you leave our site. That website's policies define your web privacy and security.
If you have any issues or concerns about these partners or linked sites, contact us at (800) 564-1588.
You are about to follow a link to [Link]. To proceed, click 'continue' below. To remain on this site, click 'cancel' below.
